The world’s leading e-commerce, payments and software platforms use YouLend to offer capital to their merchants. We provide the infrastructure behind those programmes and have so far helped fund 400,000+ businesses globally.
With one partner Dojo, payments processor targeting hospitality businesses, we've recently funded £2billion to their businesses.
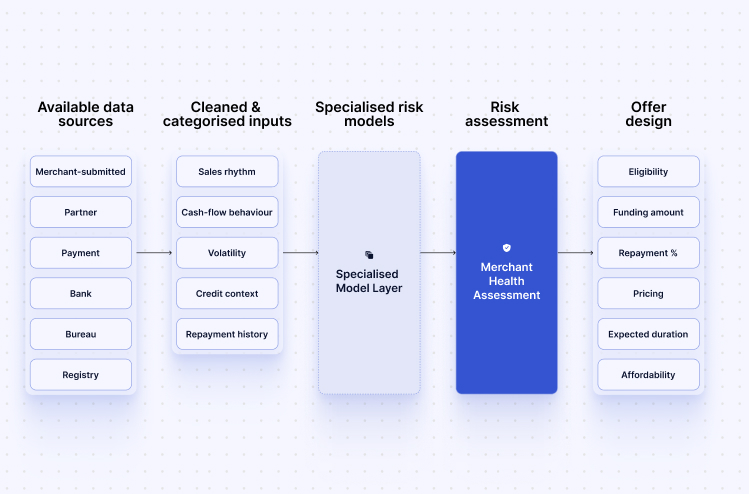
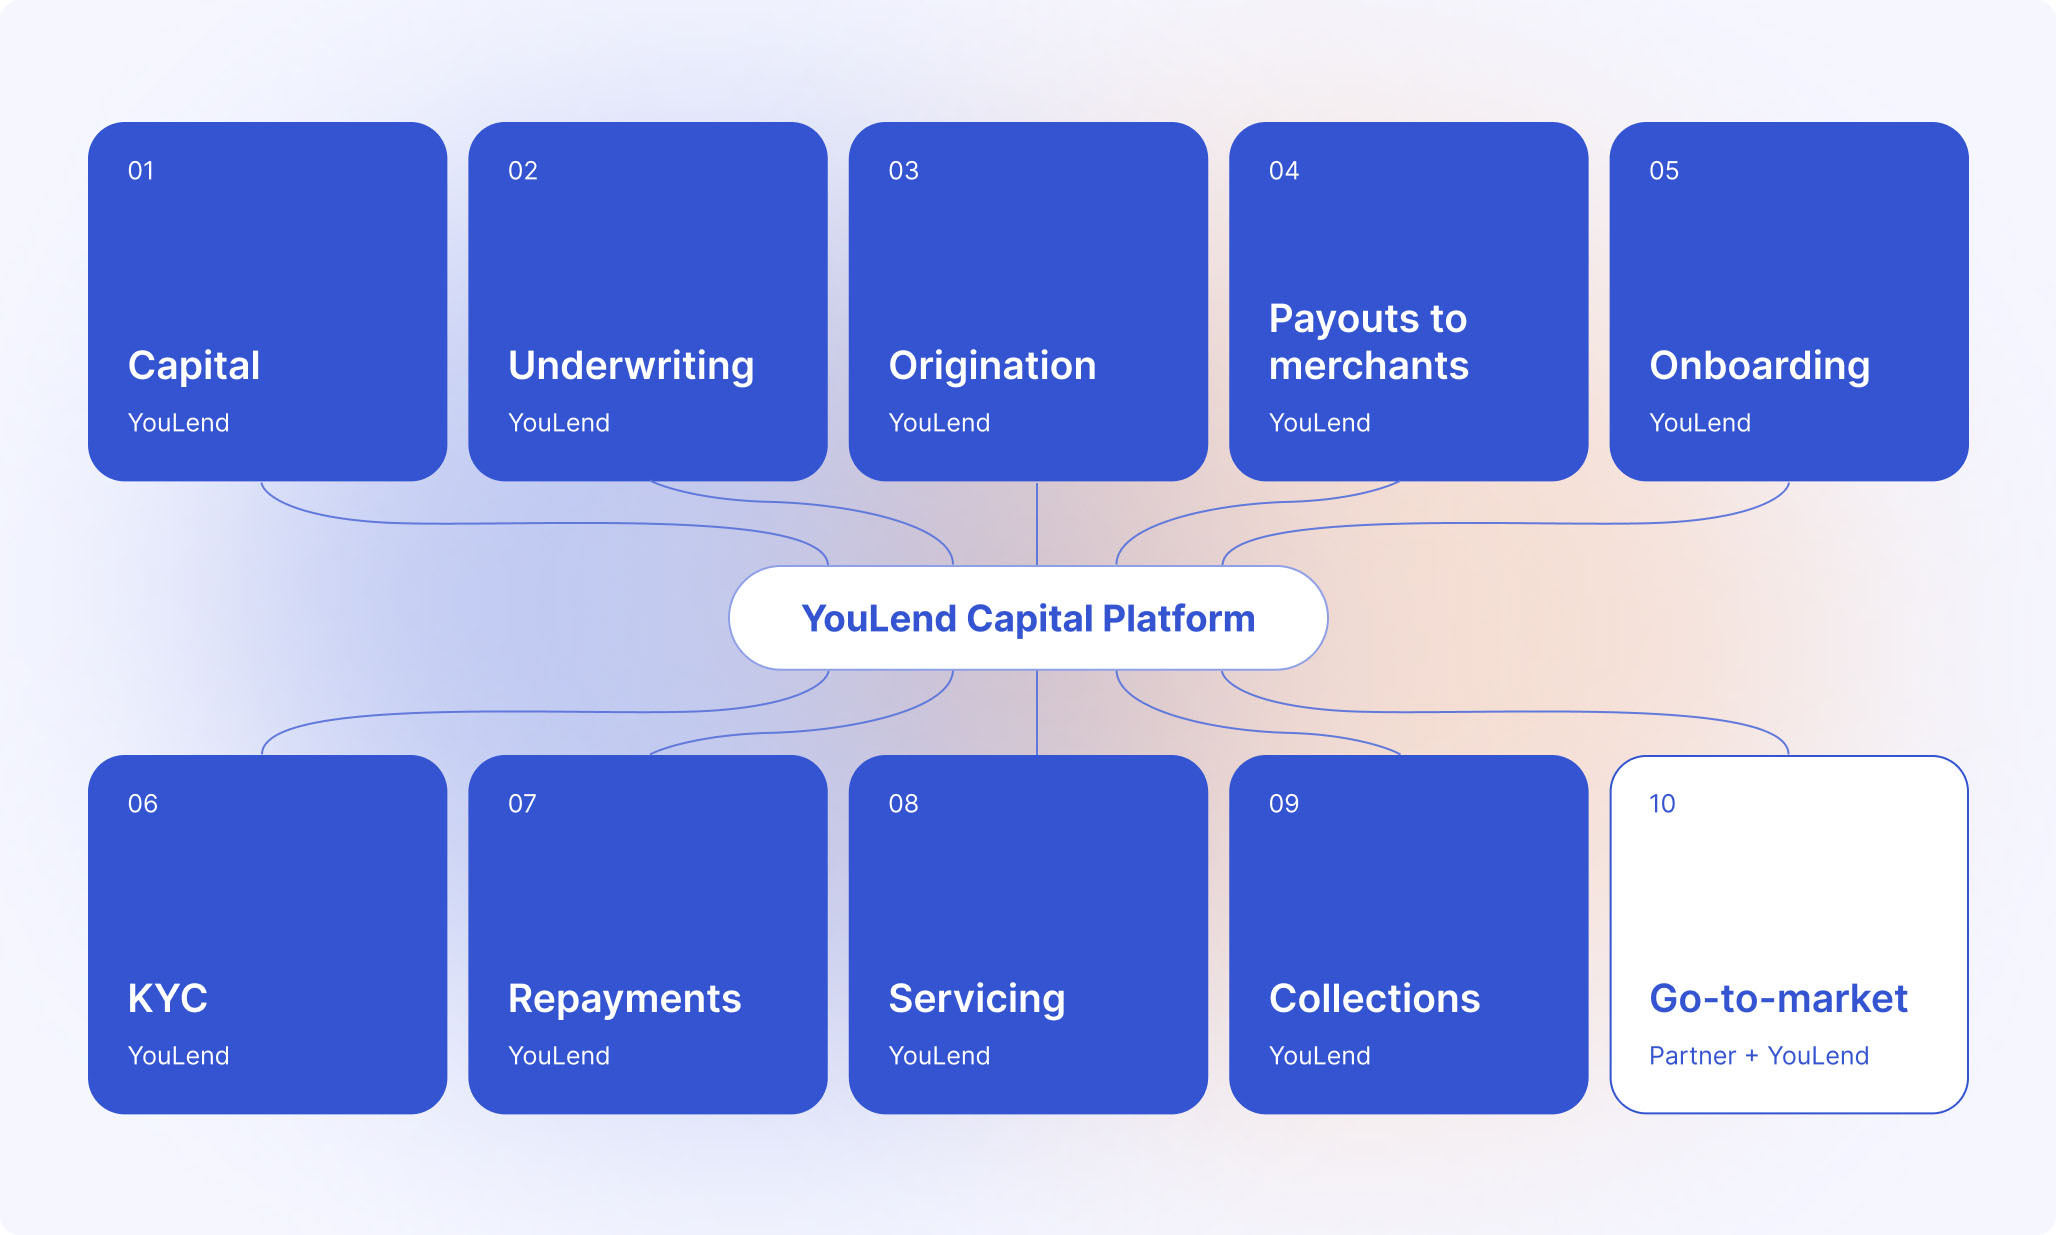
Behind this capital programme and many others sits the machinery that makes embedded financing work: capital, data, onboarding, KYC, underwriting, offers, payouts, repayments, servicing, collections, reporting, and the go-to-market strategy that bring merchants into the programme.
That is the YouLend Capital Platform.
Every partner runs embedded financing differently. Our platform gives you the capital components to build a programme around your business. You choose which parts you want to keep in-house and which you want YouLend to run, then agree the responsibilities and handoffs together.
Your data, product and existing operations shape that setup. Configurations can vary by market and adapt as your needs change.
Embedded capital has to fit the business it sits inside
Your merchants already come to you to take payments, manage bookings, send invoices or run another part of their business. A capital programme needs to fit that experience.
That includes what happens after someone clicks on an offer. The application needs the right information. The merchant needs to understand the agreement and repayments. Your support team needs to know where to send a funding question.
The programme has to fit your data, product, risk appetite, support model and commercial goals. For example, if repayment connects to an existing payment flow, both teams need to agree how collection, reconciliation and reporting will work. If a merchant contacts your account manager about their application, that person needs a clear handoff to the team that can help.
Those details belong in the programme design and leaving them unresolved gives your all teams involved a lot of work to untangle after launch let alone scale.
Capital configured
The YouLend Capital Platform brings together ten components. Nine cover the funding, merchant journey and day-to-day operation of the programme. The tenth, go-to-market, stays partner-led with you and fully supported by YouLend’s best practice and dedicated GTM teams.
For the configurable components, you and YouLend agree what your team owns in-house, what YouLend operates and where the work is shared. That configuration can change over time. The available choices depend on the programme and market, with funding arrangements and regulated responsibilities agreed separately.
The relationship stays with you
Go-to-market stays with the partner. You own the brand, merchant channels and relationship, however the rest of the programme is configured.
YouLend helps you launch, promote and develop the programme with partner-ready messaging, campaign support, sales enablement, reporting and account management. Your team can lead the merchant conversation while using YouLend's support to explain the financing and answer questions.
That support continues after the first announcement. The teams review which messages bring merchants into the programme, where applications stall and what support questions come back. Those findings should shape the next campaign and the next change to the experience.
The same platform can support different partner models
A payments platform may already have trading data and a settlement flow. Those can shape the discussion about underwriting inputs, repayments and reconciliation. The partner still needs to establish which data it can use, how the proposed flows work and who handles support.
A vertical SaaS platform starts somewhere different. A booking tool may sit close to the moment a business plans for a busy season. An invoicing platform may help a business manage outstanding payments. Either could be a relevant place to introduce capital, but access to the payment flow and usable trading data will affect how the programme can run.
That can change the initial route. A partner may choose a hosted application while it assesses demand. Another may need selected steps inside its existing product from the outset. Both need a clear view of the operating work behind the experience.
For a marketplace, the design may centre on the seller journey and payout flow. For a bank or fintech, existing credit policies, funding arrangements and servicing standards may shape the proposal.
The partner category gives us somewhere to start. The configuration comes from the business itself.
Your configuration can evolve after launch
The setup you launch with can adapt as your business needs change. You might bring selected steps into your product, change how support is shared or use different configurations across markets.
For example, a partner might start with a No Code journey, then use Embedded Components to bring selected application steps into its product. It might keep the first support enquiry with its own team, with YouLend handling financing questions. Each choice should solve a specific business or merchant need.
Changing a component also means agreeing how it works with the rest of the programme. If you bring an application step in-house, both teams need to define how information reaches YouLend, who helps when a merchant gets stuck and who owns each handoff before the change goes live.
The programme has to work for the teams running it
The Capital Platform brings the components and the operating partnership together. A partner can offer capital through its own channels and agree how the work behind it will run.
Commercial needs a credible business case. Product needs to understand the build and maintenance work. Risk and Legal need clear responsibilities. Operations needs workable processes for supporting merchants and handling repayments.
A programme that looks good in a launch announcement still has to work for those teams. The component model makes that work visible, so the teams can agree a setup they can operate and review as it develops.
See what this could look like for your platform
Bring us the business cohort you want to serve, the data you have and the parts of the programme you want to own.
We can work through a programme map covering the business journey, component ownership, route and open decisions. A scoped data exercise can then help assess the opportunity and the assumptions behind the business case, with data use and handling agreed first.
That gives your teams something concrete to assess: a proposed programme, the work it involves and the evidence needed to take it forward.
See what this could look like for your platform.